Approve
the first program
Bound the opportunity clearly before capital is deployed.
- Select the first product and target segment
- Agree risk appetite and policy guardrails
- Align operating scope and commercials
 NBFC Calculator
Enter the operating assumptions for the 12-month NBFC model. The defaults mirror the source workbook and can be reset at any time.
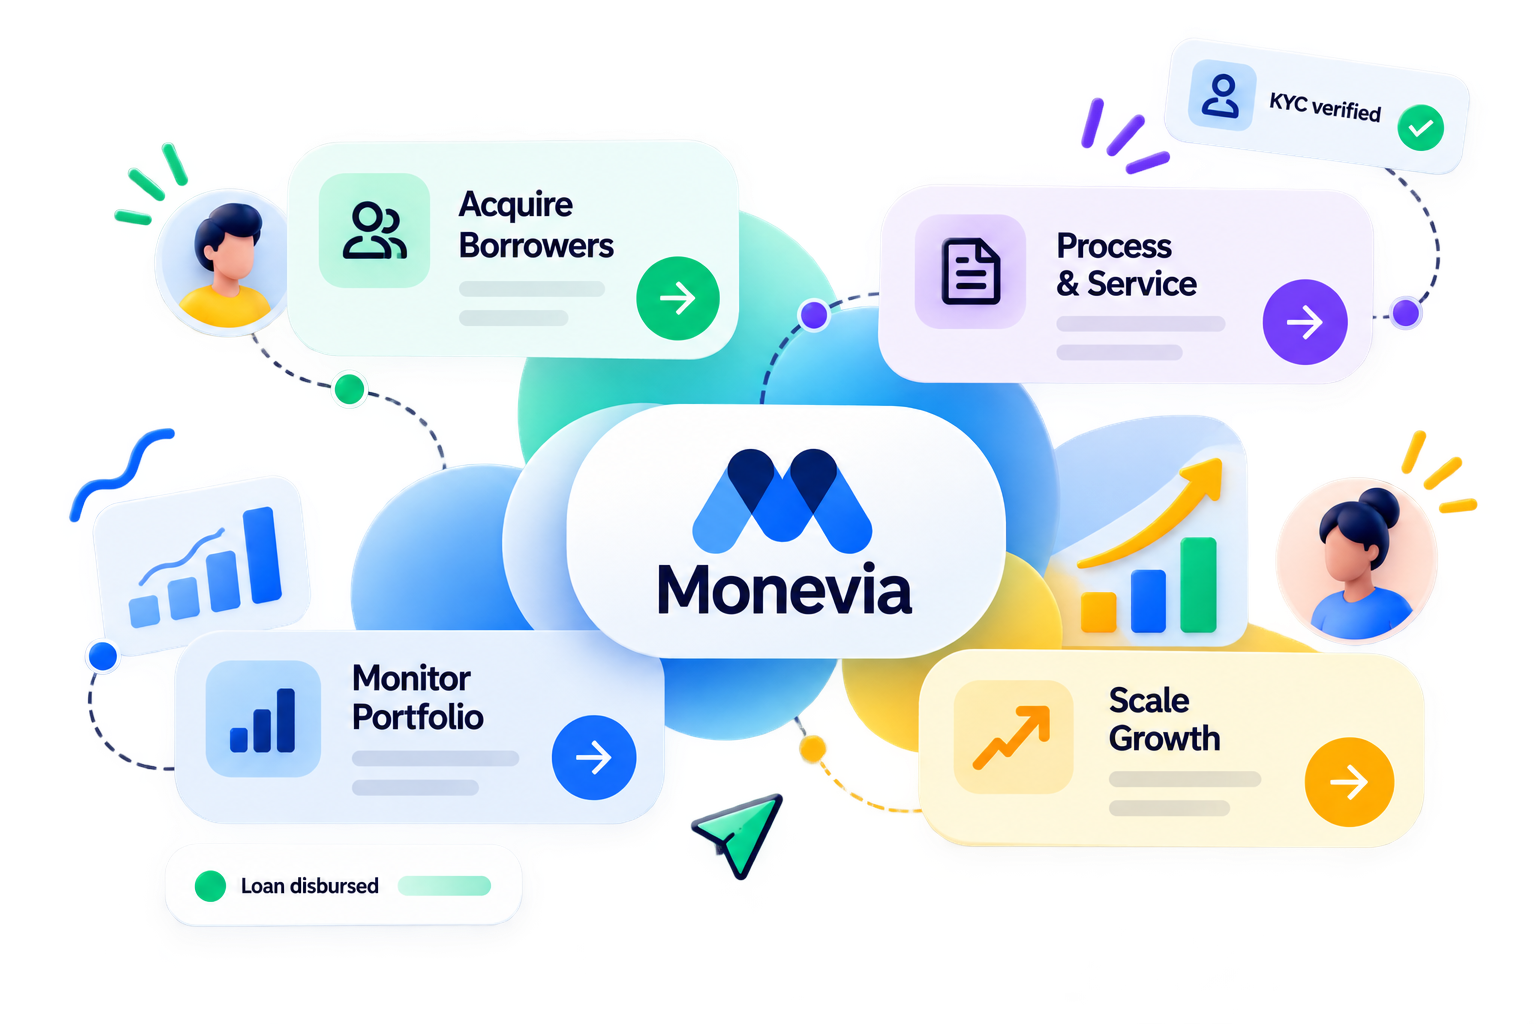
Monevia powers the operating layer behind NBFC growth — from borrower acquisition to servicing and portfolio visibility, while you retain control of capital, policy and credit decisions.
Overview • Partnership journey
At board level, the Monevia model can be understood as a controlled four-step pathway: approve a defined program, activate one operating stack, monitor the book with full visibility and then scale only when the early evidence is strong.
Bound the opportunity clearly before capital is deployed.
Move sourcing, onboarding, servicing and collections into one coordinated model.
Review growth, asset quality and control metrics from the first cohort onward.
Expand only after the book shows acceptable economics and control performance.
It gives the NBFC one accountable operating partner, preserves lender decision rights and creates a cleaner reporting line from portfolio performance back to management and the board.
Approve a defined product, launch in a controlled cohort, learn from live data and then expand only when the economics, controls and service quality are proven.
02 • What Monevia brings
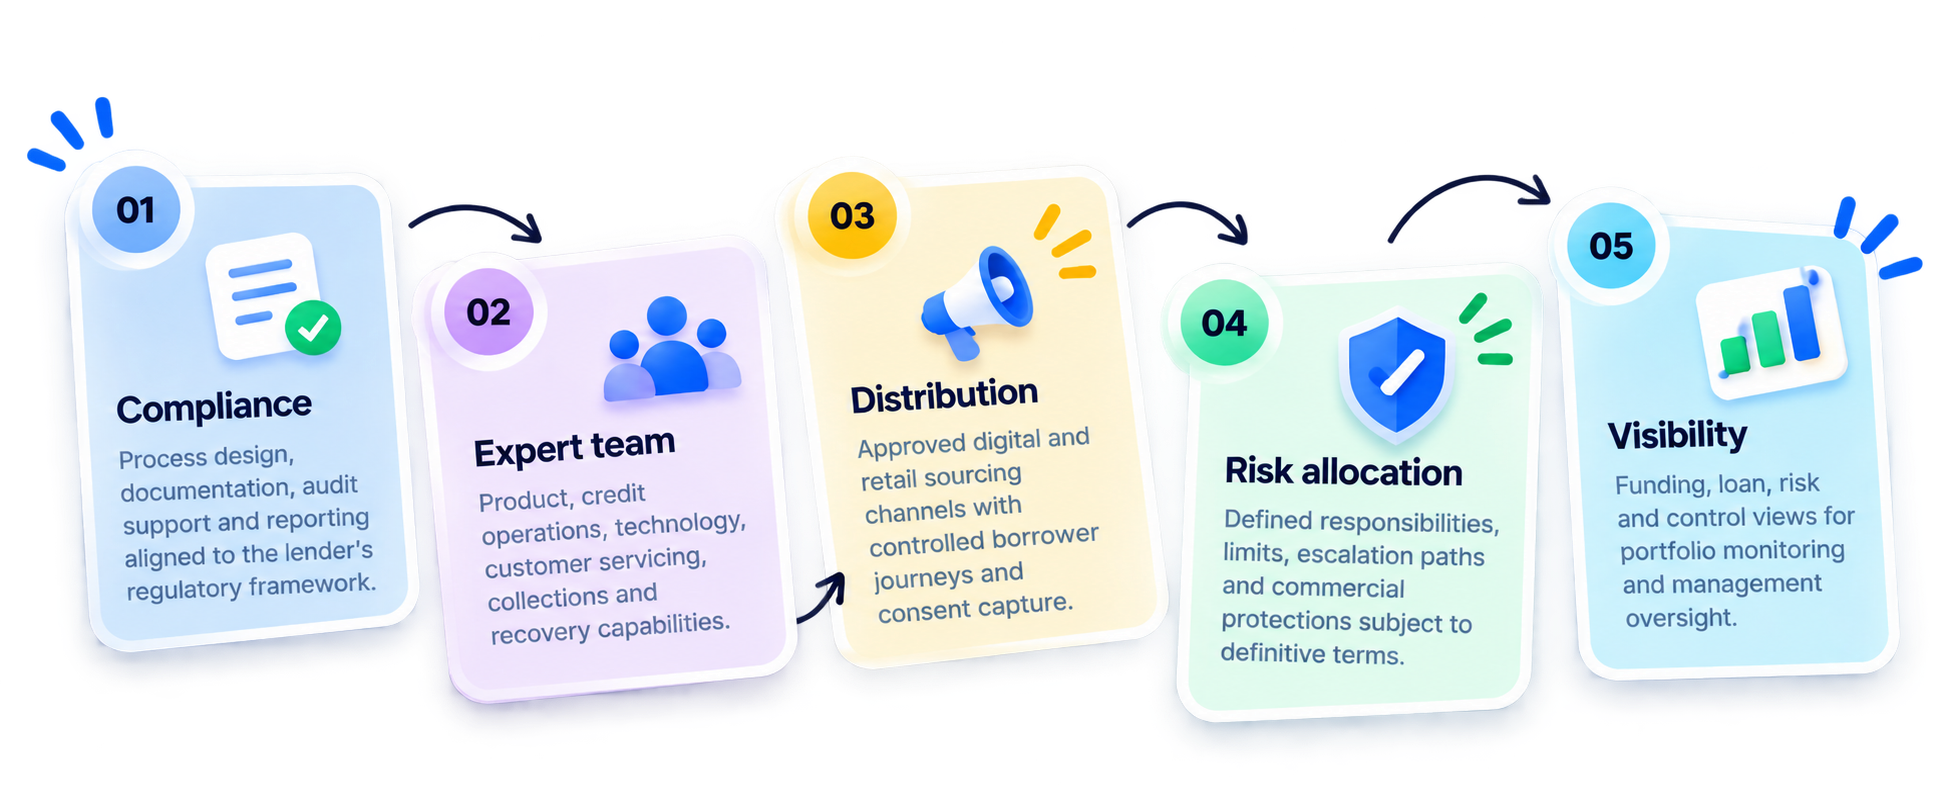
Five capabilities sit behind the partnership: compliance-aligned process design, lending expertise, distribution, risk allocation frameworks and portfolio visibility.
03 · Governance by design
The structure preserves the regulated entity’s decision rights while giving Monevia clear accountability for approved operational execution.
Capital, product approval, pricing, eligibility, exposure limits, sanction or decline and regulatory oversight.
The partnership is designed around a deliberate distinction between regulated lending decisions and outsourced operating execution.
Customer acquisition, application capture, verification workflows, underwriting support, servicing, collections operations and MIS.
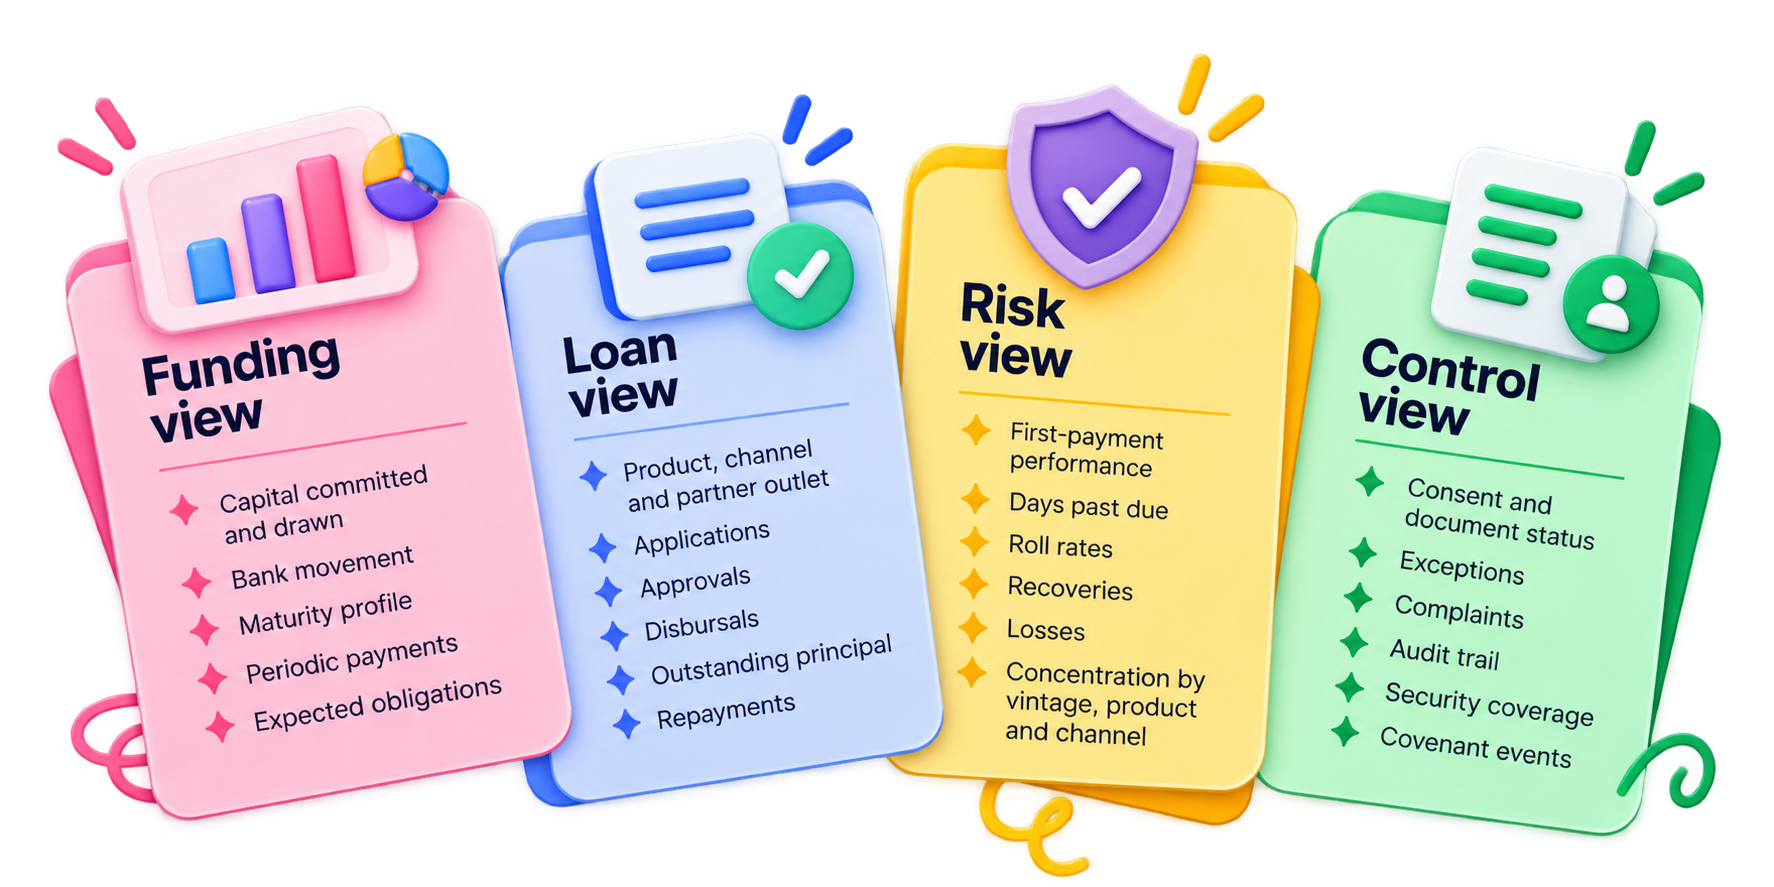
Operating data, exceptions, complaints, controls and performance are structured for review by risk, compliance and management teams.
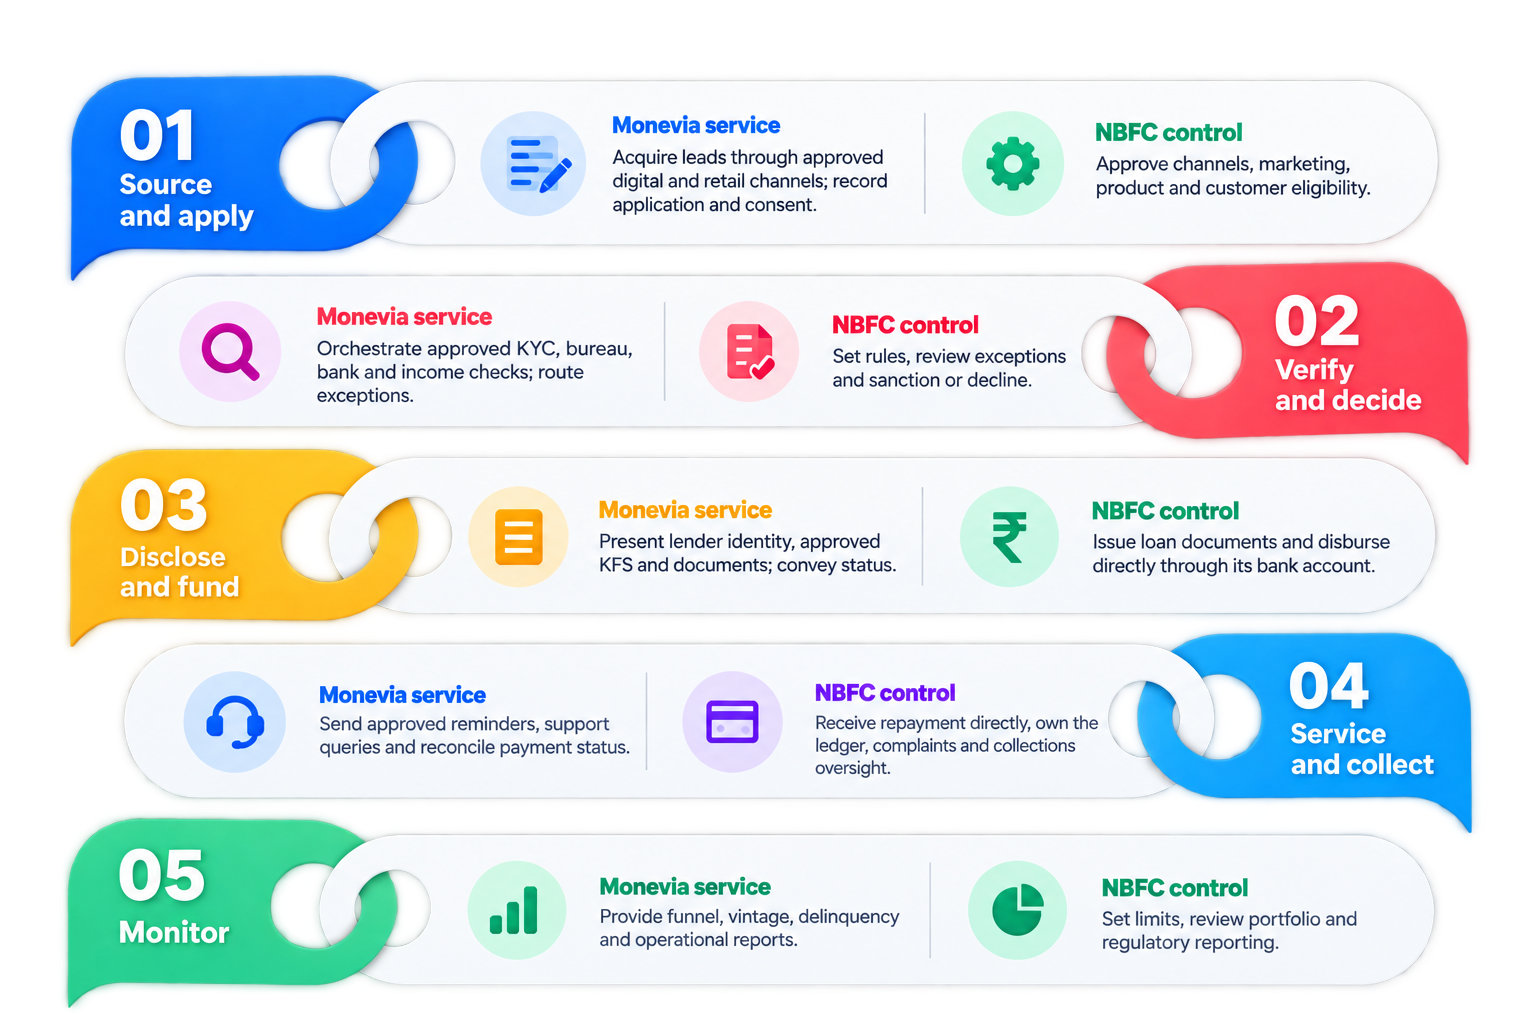
04 • End-to-end lending model
Each stage is built around an approved Monevia
service layer and an explicit NBFC control point.
05 · Product launch and scale
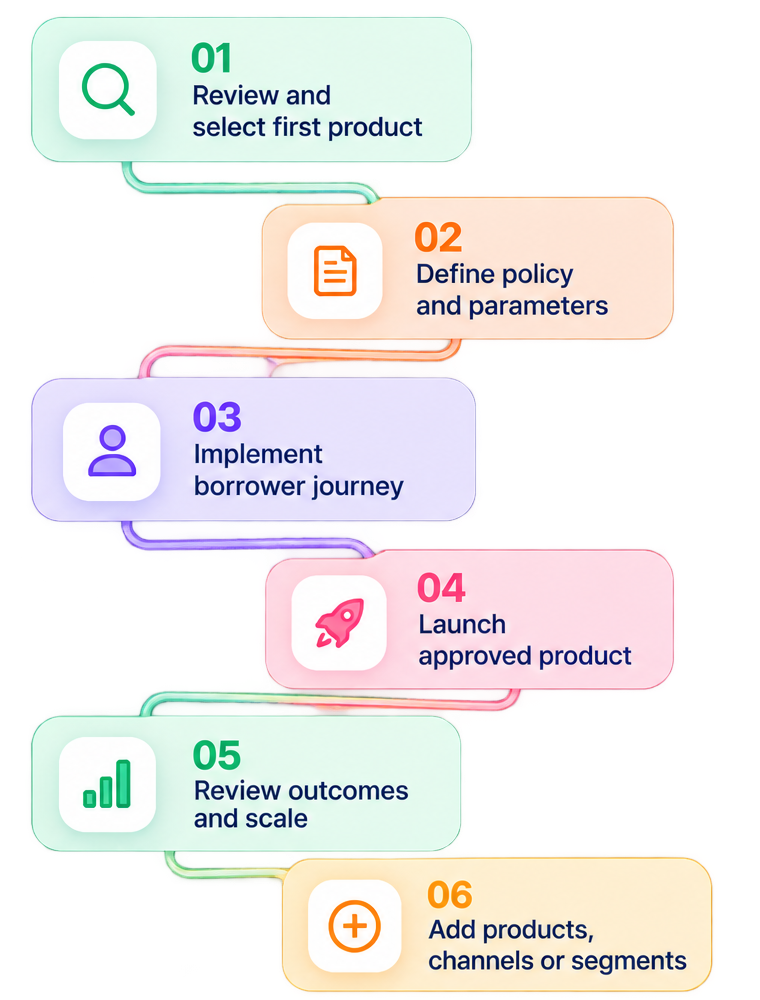
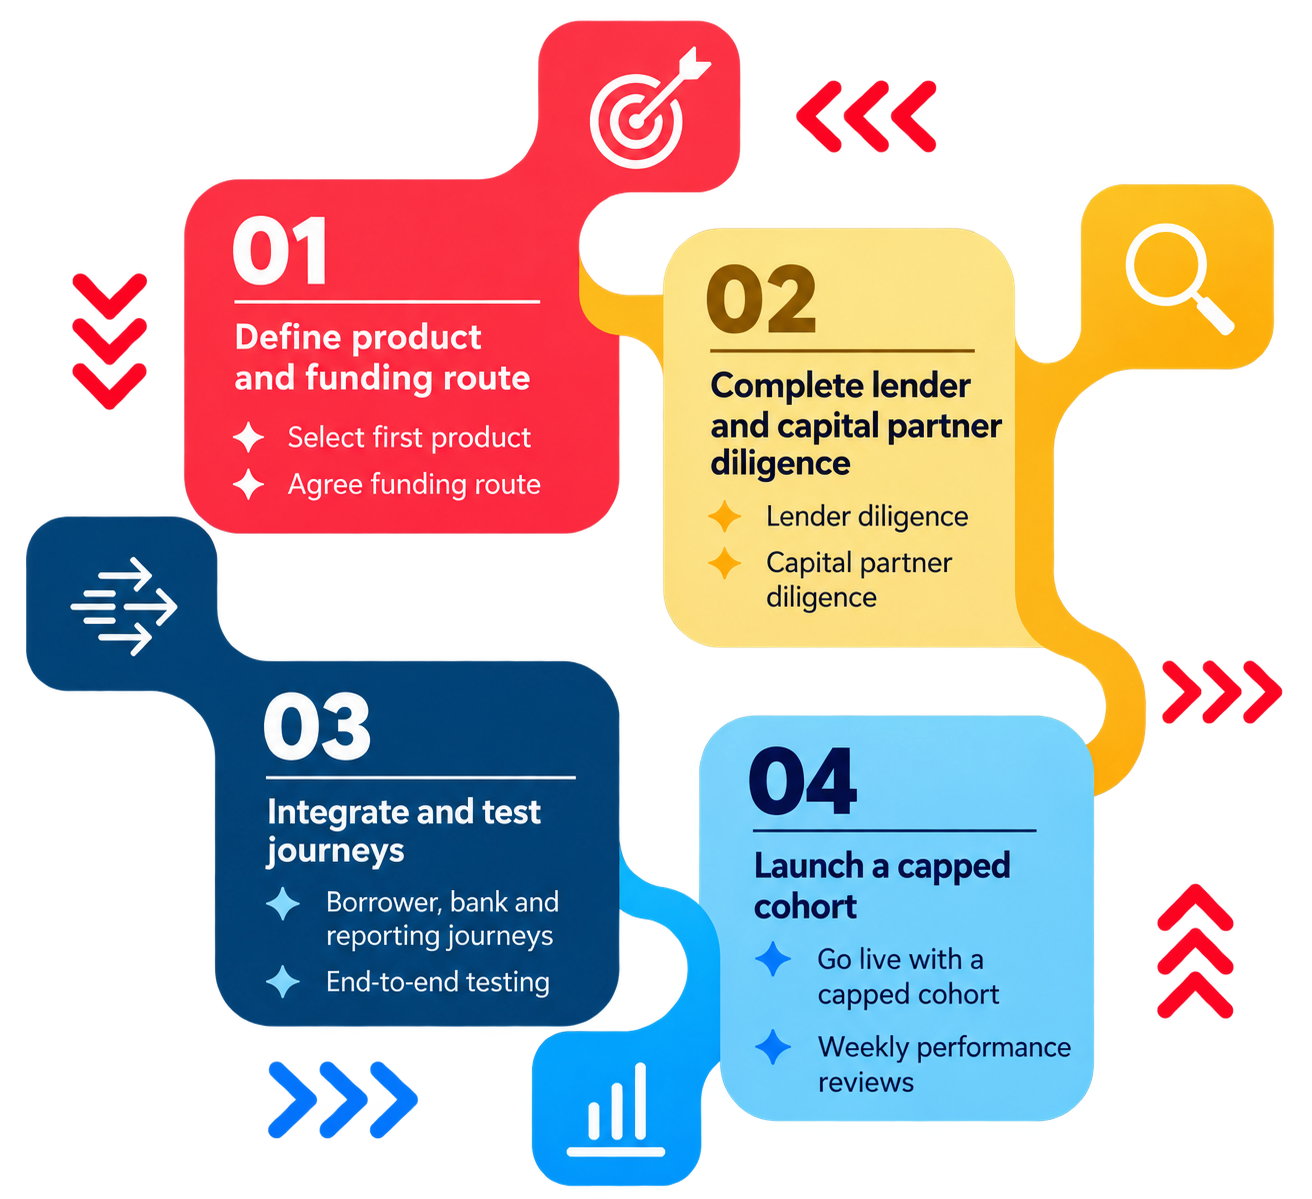
The launch path is intended to reduce execution risk: select the first product, define policy, implement the borrower journey, launch a controlled cohort and scale after performance review.
06 · Risk, protection and transparency
08 · Execution pathway
Move from discussion to evidence quickly, while
keeping policy, compliance and integration sign-offs
explicit.
Let’s discuss the product, operating model and partnership route.
Workbook-aligned calculations based on your current assumptions.